Industry
Seasonal cash-flow planning for Atlantic Canada and the North
Seasonal cash flow planning Canada: how ice roads, ferries, Halifax and St. John's tourism and Whitehorse monthly projections shape lender-ready plans.
What to take away
- Seasonal cash flow planning Canada works best when the month is the unit of analysis, not the year: twelve columns, each with its own revenue, freight and payroll assumptions.
- Ice roads and ferry schedules are operational constraints that belong in the plan, because they set when inventory arrives and when cash leaves.
- Halifax and St. John's tourism seasonality compresses most Atlantic revenue into a few months, so working capital has to be arranged before the season, not during it.
- Whitehorse monthly projections need a winter freight build, a summer construction and tourism peak, and a shoulder season that is genuinely thin.
- Lenders test seasonal borrowers with GDS and TDS ratios, and the debt-service section works both on the trough-month numbers.
- The Index of Remoteness and the CMHC Northern Housing Report give outside evidence for market size and housing cost in Northern plans.
Why monthly projections break in Atlantic Canada and the North
An annual projection hides the problem. A seasonal business can show a healthy year and still miss payroll in March. The fix is a twelve month build where each month carries its own assumptions about volume, price, staffing and freight.
That build starts with the same discipline as any financial projections file: three linked statements, one assumptions page, and a clear note on which assumption moves the result most.
Atlantic Canada and Northern Canada add three variables that southern Canadian plans rarely carry. Weather windows decide when goods move. Ferry schedules decide when they arrive. Distance decides what they cost.
A Halifax café and a Whitehorse building supplier share the same structural issue: revenue is uneven, costs are not. Rent, insurance and core wages run all year. The plan has to show how the trough is funded.
Start by listing every month where cash out exceeds cash in.
Trough month, funding source, repayment month
- Which month is the trough, and how deep is it?
- What funds that monthreserves, a line of credit, supplier terms or owner capital?
- When does the repayment happen, and from which month's surplus?
Write the answers into the assumptions page.
Ice roads, ferry schedules and freight timing in the operations plan
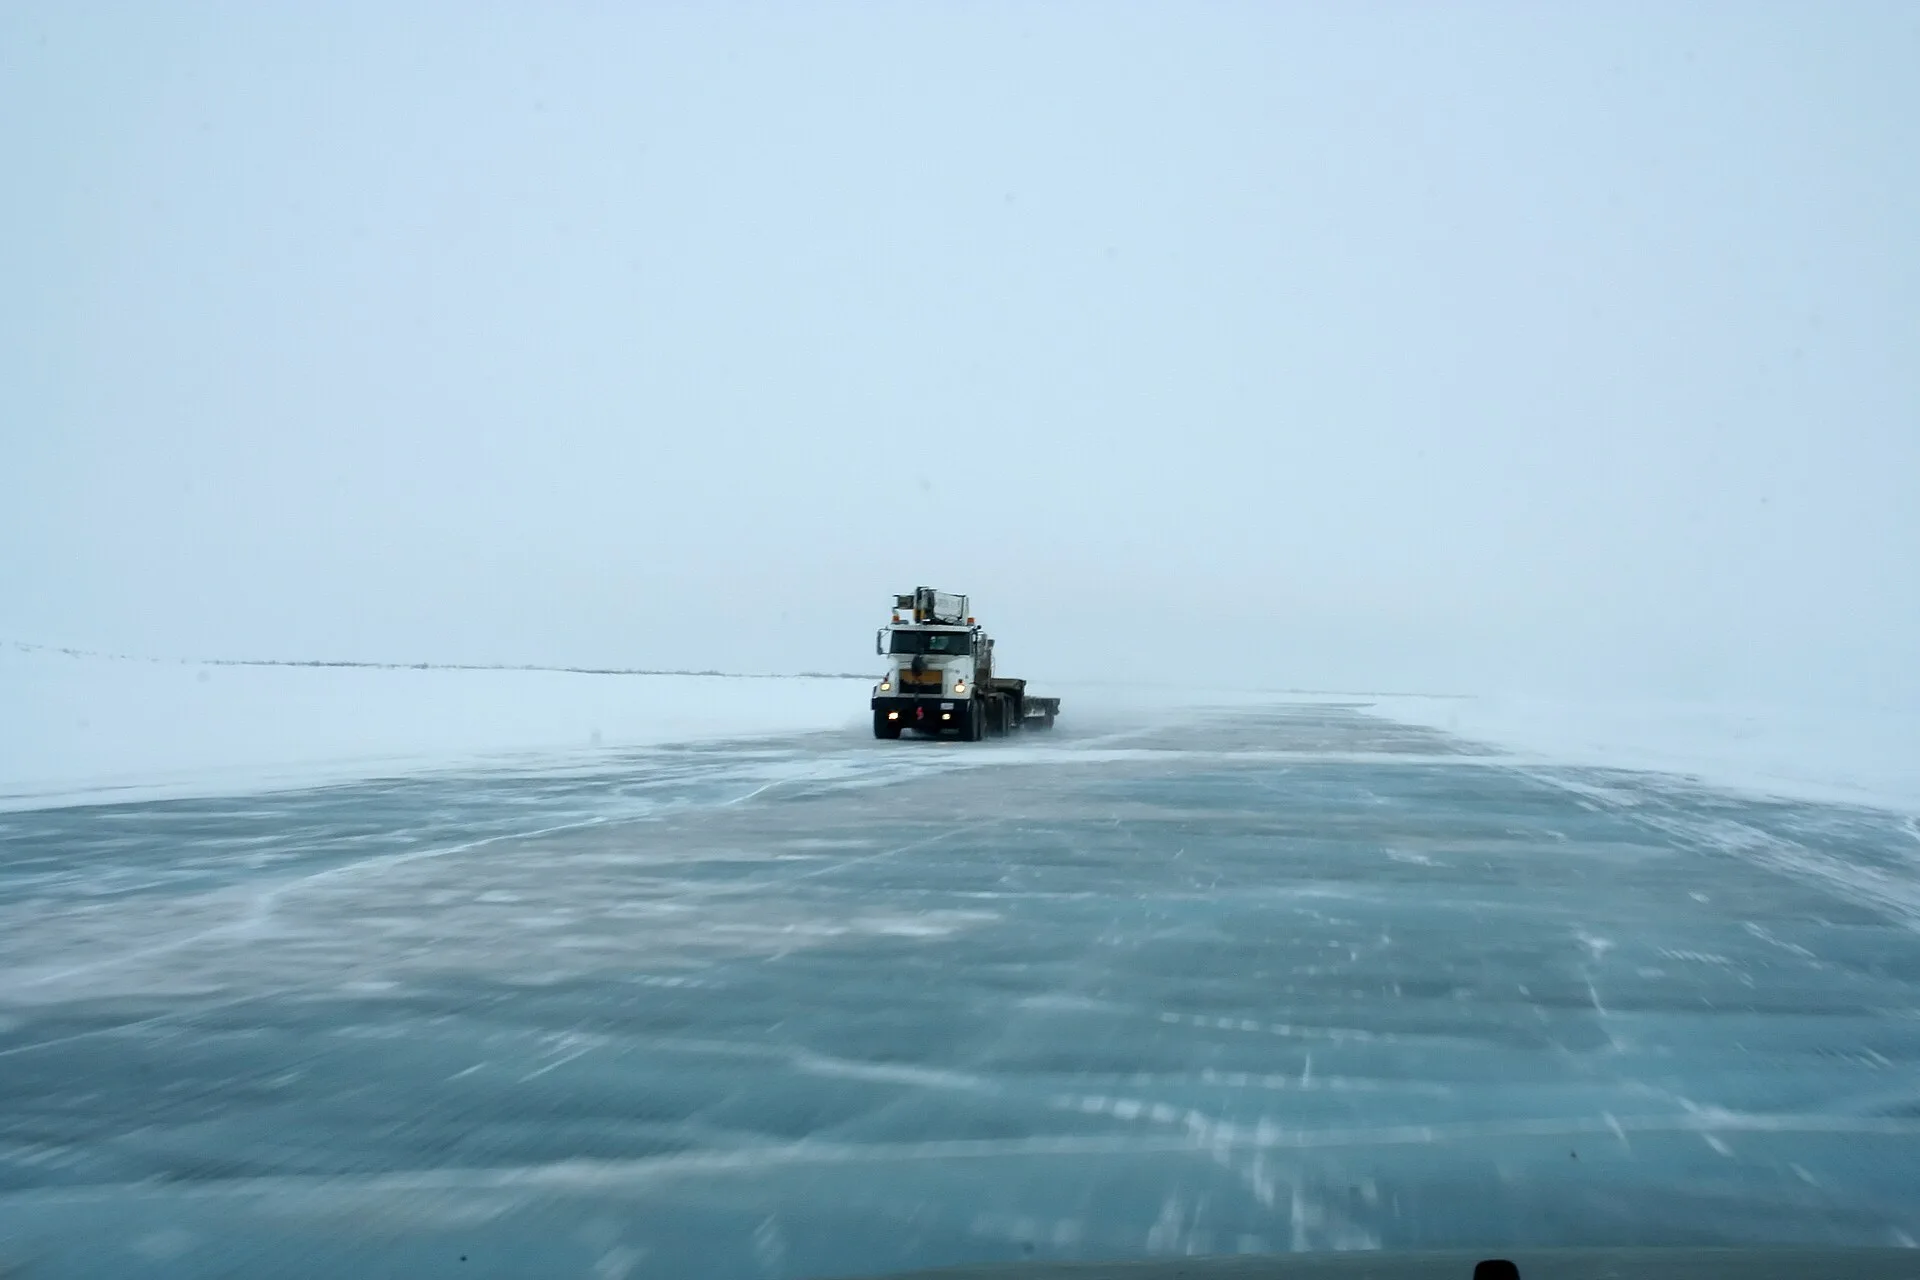
Ice roads open for a short winter window. When they close, communities that depend on them switch to air freight or wait. That single fact reshapes inventory planning for any Northern operator.
A Yellowknife or Nunavut supplier that brings in a year of stock on the winter road carries the cost of that stock for months. The plan must show the purchase month, the storage cost and the working capital gap.
Ferry schedules do the same work on the Atlantic coast. Marine Atlantic crossings between Nova Scotia and Newfoundland set delivery windows for St. John's businesses, and a missed sailing can push a shipment by days.
This is where an operations plan earns its place. Trace one order end to end and name the constraint: the sailing, the road window, the supplier cut-off. Then price the delay.
The two lines to add: holding cost and backup premium
Operations plan freight checklist
- Freight mode by season with cut-off dates
- Lead time supplier to shelf, peak and shoulder
- Storage or holding cost from buying ahead
- Backup mode when primary route closes
- Insurance and spoilage on stock held
Two numbers from this list belong in the cash flow: the holding cost and the backup premium. Both are easy to omit and both are real.
For operators across Atlantic Canada and Northern Canada, this freight calendar is the first constraint a lender queries, because a large winter purchase sits in the trough month.
A worked freight example
A Whitehorse retailer buys a big spring stock of building hardware in February on the winter road, paying $60,000. Most of it sells by July, so the average balance carried is about $30,000.
Storage and insurance run about $300 a month. Carrying that stock at a 9 percent cost of capital adds about $225 a month, so holding cost is roughly $525 a month, or about $3,150 across the six months.
Air freight is the backup. Typical scheduled cargo rates into Whitehorse run about $2 to $5 per kilogram, against roughly $0.50 to $1.00 per kilogram by road. A 1,000 kilogram reorder that flies adds $1,500 to $4,000. Confirm the rates with your carrier before you use them.
The cash flow entry is not the $60,000 alone. It is the February payment, the monthly holding cost, and the extra draw on the operating line that funds the gap before summer sales.
Tourism seasonality for Halifax and St. John's businesses
Halifax and St. John's both run on a compressed visitor season, but the shape differs. Halifax draws cruise calls and convention traffic across a longer shoulder. St. John's concentrates more of its trade in the summer months and depends heavily on air access and ferry arrivals.
For a restaurant, tour operator or boutique hotel, that means revenue in four or five months must carry twelve months of fixed cost. The plan should show the split explicitly rather than averaging it away.
Staffing follows the same curve. Seasonal hiring, training and retention costs land before the revenue does, which is a cash outflow in the shoulder month, not the peak.
Where the working capital comes from
Atlantic businesses have funding options that a generic plan ignores. The Atlantic Canada Opportunities Agency runs the Regional Economic Growth through Innovation (REGI) programme. Its Business Scale-up and Productivity stream funds projects that raise productivity, capacity or exports, and its Atlantic funding programme pages set out eligibility.
Eligible applicants are for-profit businesses in Atlantic Canada. ACOA sets the contribution rate and repayment terms per project, so quote the current stream guide rather than a remembered percentage.
Provincial support matters too. Nova Scotia's provincial business department publishes the business planning and lending context that provincial programs sit inside, which is useful when a plan has to match a specific program's criteria.
The Nova Scotia Business Fund, delivered by Nova Scotia Business Inc. (NSBI), offers capital loans and payroll rebates to employers in the province. The NSBI Innovation Rebate is a refundable tax credit on eligible capital costs. Neither NSBI nor ACOA publishes one universal threshold, so quote the terms of the stream you are applying to.
A seasonal operator should show the line of credit drawn in the shoulder, repaid in the peak, and the interest cost of that draw. Lenders read that pattern as competence.
The revenue-index table: low, peak and falling months
| Month | Revenue index | Fixed cost | Cash position |
|---|---|---|---|
| January | Low | Full | Negative |
| April | Low | Full | Negative |
| July | Peak | Full plus seasonal | Strong positive |
| August | Peak | Full plus seasonal | Strong positive |
| October | Falling | Full | Break-even |
| December | Low | Full | Negative |
Build the same table with your own numbers. The index column is the argument; the cash position column is the ask.
Northern cash-flow planning with Whitehorse as the worked case
Whitehorse sits between two economies. Tourism and construction peak in summer. Government, mining services and freight move through the year, with a winter logistics push.
A Whitehorse monthly projection should separate these streams. Tourism revenue has a short window. Contract and government work is steadier but slower to pay, which creates a receivables gap rather than a revenue gap.
The twelve-month Whitehorse build: revenue, freight, payroll and cash
Whitehorse monthly build
- List revenue by stream
- Assign each stream to billing months
- Layer winter freight purchase and holding cost
- Add payroll including seasonal training weeks
- Show line of credit draw and repayment
- Test against late spring and short ice road
The figures below are one worked illustration; replace each with your own quotes and contracts. Opening cash on 1 January is $35,000, and the cash column is month end cash before any draw on the operating line. Freight covers inbound and outbound freight together. Payroll includes the seasonal crew from May to September.
| Month | Revenue | Freight | Payroll | Cash position |
|---|---|---|---|---|
| January | 90,000 | 6,000 | 22,000 | 23,000 |
| February | 100,000 | 12,000 | 22,000 | -52,000 |
| March | 110,000 | 7,000 | 22,000 | -56,000 |
| April | 135,000 | 8,000 | 23,000 | -51,000 |
| May | 180,000 | 10,000 | 30,000 | -35,000 |
| June | 240,000 | 13,000 | 32,000 | 33,000 |
| July | 280,000 | 14,000 | 33,000 | 117,000 |
| August | 265,000 | 13,000 | 33,000 | 165,000 |
| September | 215,000 | 11,000 | 30,000 | 196,000 |
| October | 165,000 | 9,000 | 26,000 | 210,000 |
| November | 115,000 | 7,000 | 23,000 | 207,000 |
| December | 90,000 | 6,000 | 22,000 | 194,000 |
February carries the $60,000 winter-road stock purchase, which is why its cash position drops hardest. The operating line peaks at $56,000 at the end of March and is repaid in full by July.
The format matters as much as the numbers. A clean layout that a lender can scan is worth the effort, and this start-up visa business plan canada guide covers the layout choices that make a monthly build readable.
The sensitivity that decides the plan
Run the model with the ice road open two weeks less than usual. If the plan still funds payroll, the plan holds. If not, the shortfall is the number to solve before submission.
Air freight is the number that moves. At $1,500 to $4,000 extra per 1,000 kilograms, a 5,000 kilogram shortfall adds $7,500 to $20,000 to the February cost.
That test also belongs in the business plan risk section, because it shows a lender you have priced the weather rather than assumed it away.
Using the Index of Remoteness and the Northern Housing Report as evidence
Outside data strengthens a plan for Atlantic Canada and Northern Canada when it is used to size a market or justify a cost, not as decoration.
Statistics Canada publishes an Index of Remoteness that scores communities on their distance from population centres and the services those centres provide. The published index is the 2019 Statistics Canada paper, and the score runs from 0 for a community beside a large population centre to 1 for the most remote.
For a plan, it is a defensible way to explain why freight, staffing and service costs run above southern benchmarks.
It also helps with market sizing. A high remoteness score supports a claim about a small, captive customer base and the pricing that base will bear.
Housing cost is the other Northern planning variable. CMHC's Northern Housing Report tracks supply, demand and cost conditions across Northern communities, which matters when staff housing is part of your operating cost.
The report comes out each year, so the citation names the edition year. Its community tables give average rent and vacancy for each Northern centre, and the staff housing line in the plan should quote the Whitehorse row.
A typical Whitehorse two-bedroom rent in recent CMHC reporting sits in the $1,500 to $1,900 a month range, so check the current edition before you set the allowance.
If you house seasonal or permanent staff, that cost belongs in the monthly build, not in a footnote. The report gives you a citable basis for the figure.
Turning data into a plan line
- Use the remoteness score to justify a freight and service cost premium.
- Use housing data to set a staff housing allowance or lease cost.
- Cite both once, in the assumptions page, with the source year and the figure they support.
- Keep the rest of the plan in your own operational language.
Sector-specific conventions vary, and the parts worth copying from comparable businesses are covered in plans by industry, which is a faster route than rebuilding a template from scratch.
Debt-service figures lenders will apply to a seasonal business
A seasonal borrower is judged on debt service, and Canadian lenders typically work with two ratios. Gross Debt Service compares housing or occupancy costs to income. Total Debt Service adds all other debt payments to that total.
CMHC sets out how these are how CMHC calculates GDS and TDS, and the same logic shapes how a commercial lender reads a seasonal file: can the trough month still carry the payment?
For a business plan, the useful move is to show the ratio in the trough month, not the peak. A plan that services debt comfortably in August proves little.
Trough-month cover and the bridging facility
Item / What the plan shows
- Trough month
- March: revenue of $110,000, outflows of $104,500 before debt service, and cash available for the $10,000 payment of $5,500, or 0.55 times
- Gross Debt Service
- Occupancy of $9,000 in March, or 8.2 percent of the month's revenue; 9.1 percent on the annual figures
- Total Debt Service
- Occupancy plus the $10,000 payment, or 17.3 percent of March revenue; 15.1 percent on the annual figures
- Bridging facility
- A $100,000 revolving operating line, drawn to $56,000 at 31 March, interest only to June, principal repaid in four payments from July to October
What to show the lender
Item
- Annual debt service
- Total payments across twelve months
- Trough-month cash
- Lowest monthly cash position
- Coverage in trough
- Trough cash against payments due
- Reserve or facility
- Line of credit covering the gap
What the plan shows
- Annual debt service
- Trough-month cash
- Coverage in trough
- Reserve or facility
If the trough month cannot carry the payment, say so and show the facility that bridges it. A stated gap with a plan reads better than a smoothed average.